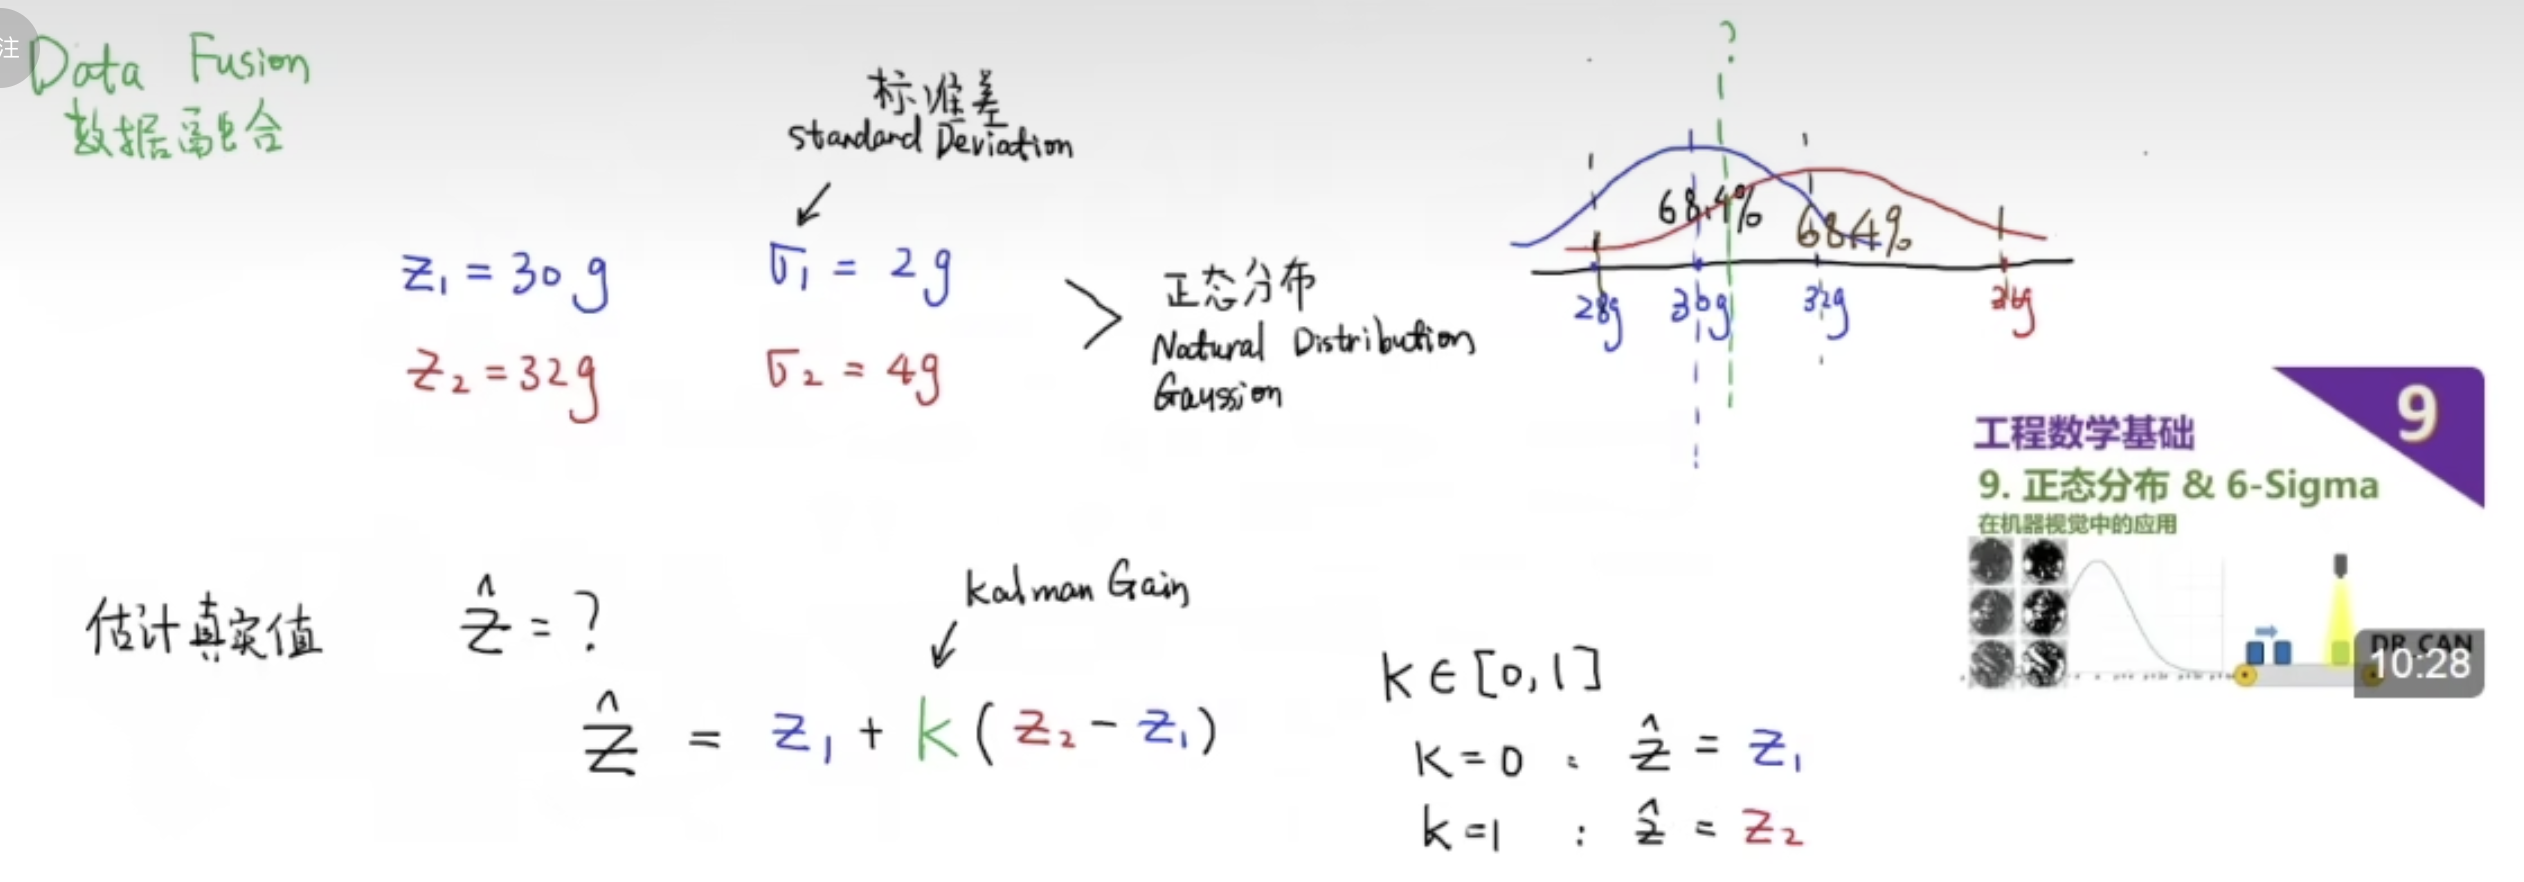
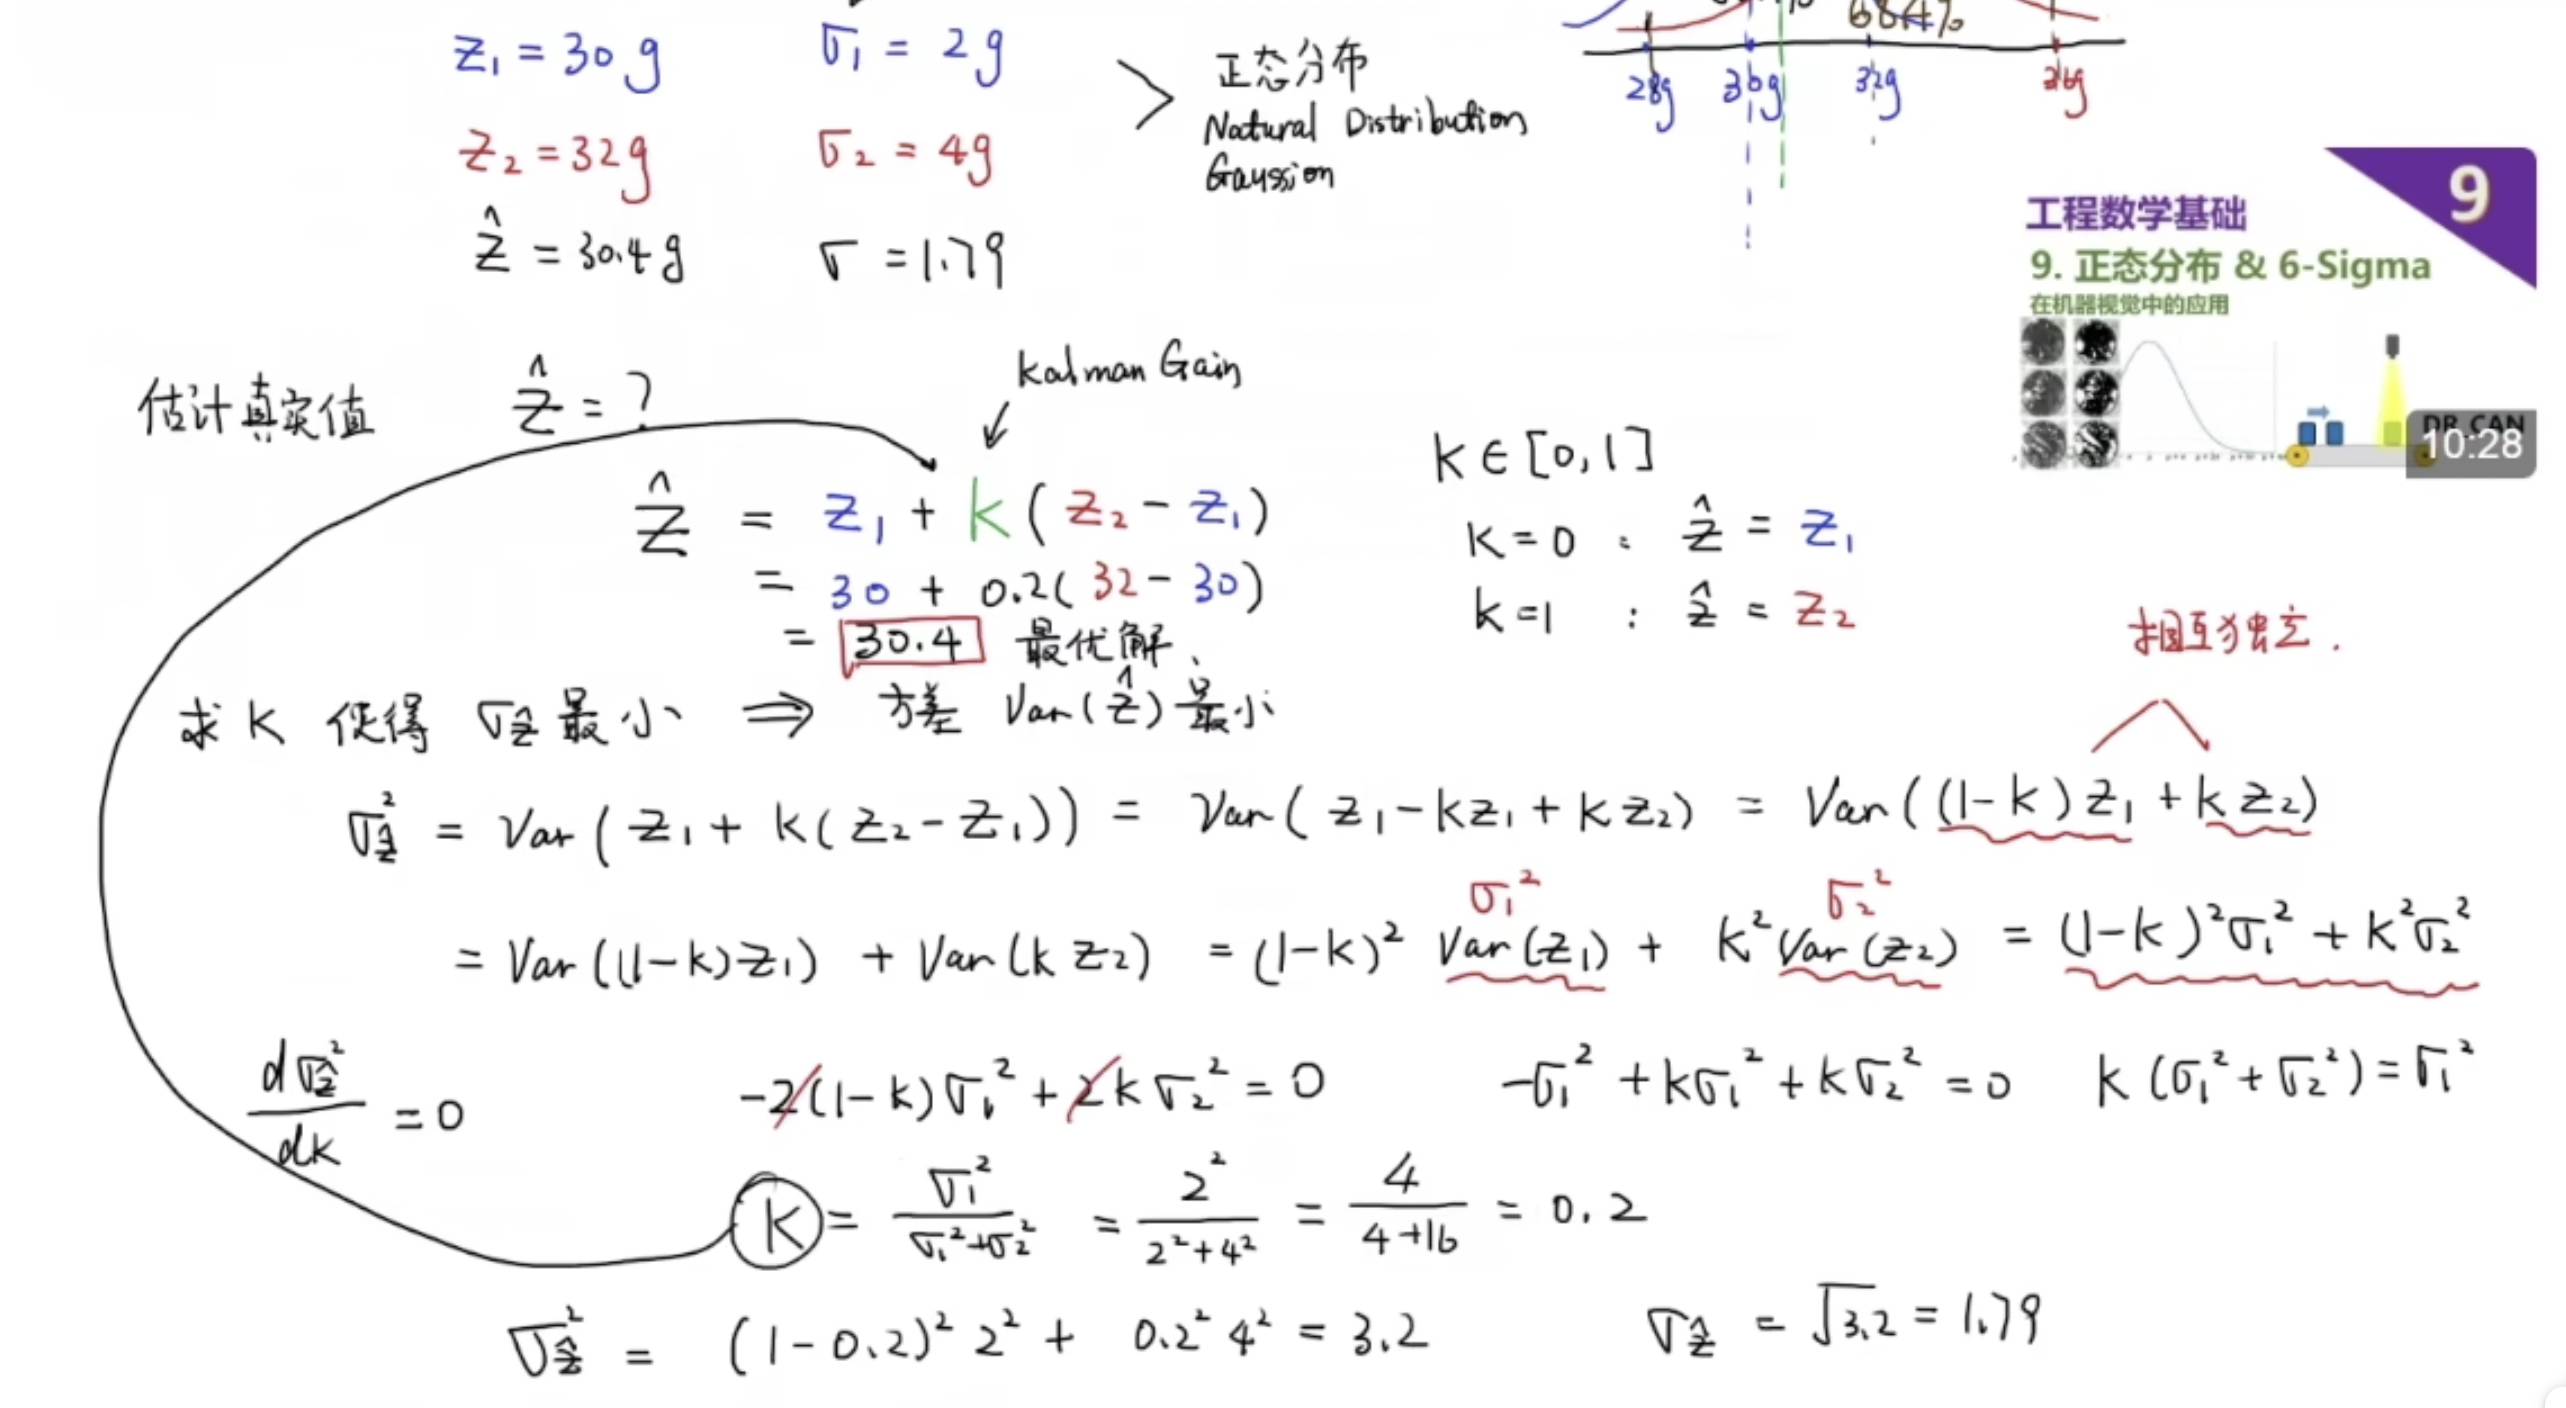
The Kalman filter is essentially a process of fusing sensor measurements with values derived from a mathematical model to approximate the true value, which is why it is often called a sensor fusion algorithm
- For a Gaussian distribution, the smaller the variance, the closer the values are to the expected value (here the expected value is 0), and the sharper the peak
1. Data fusion
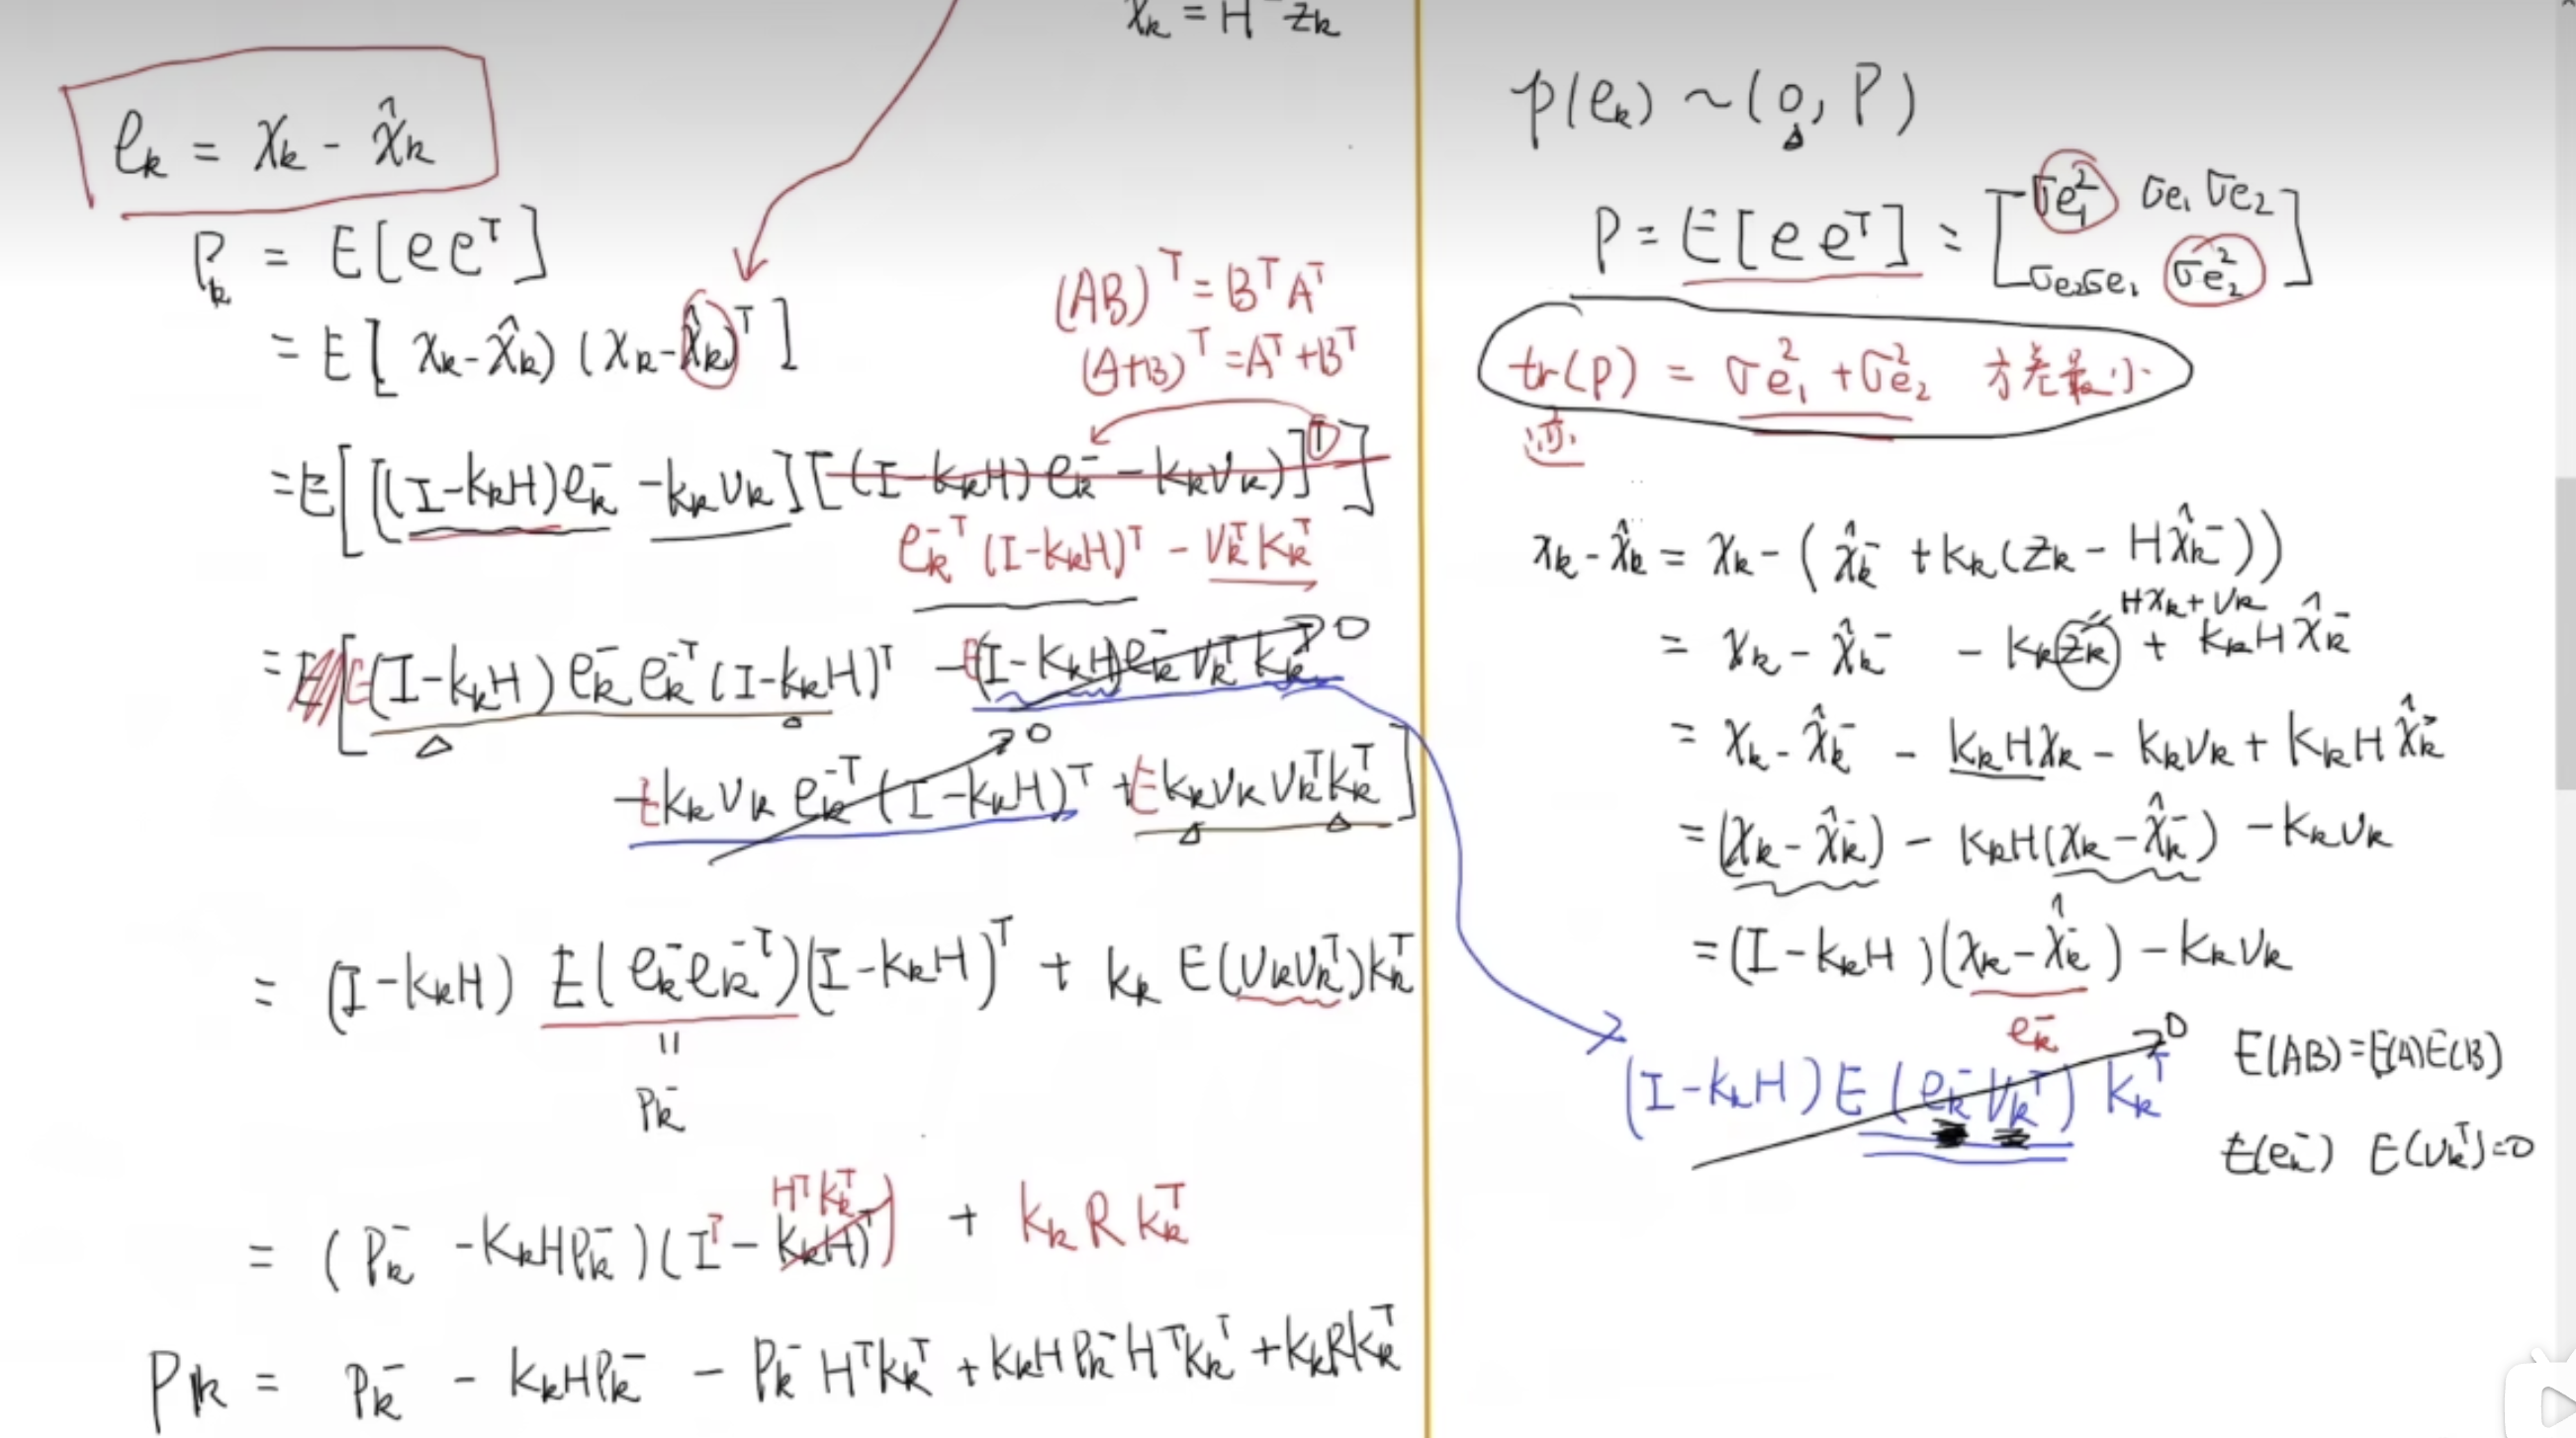
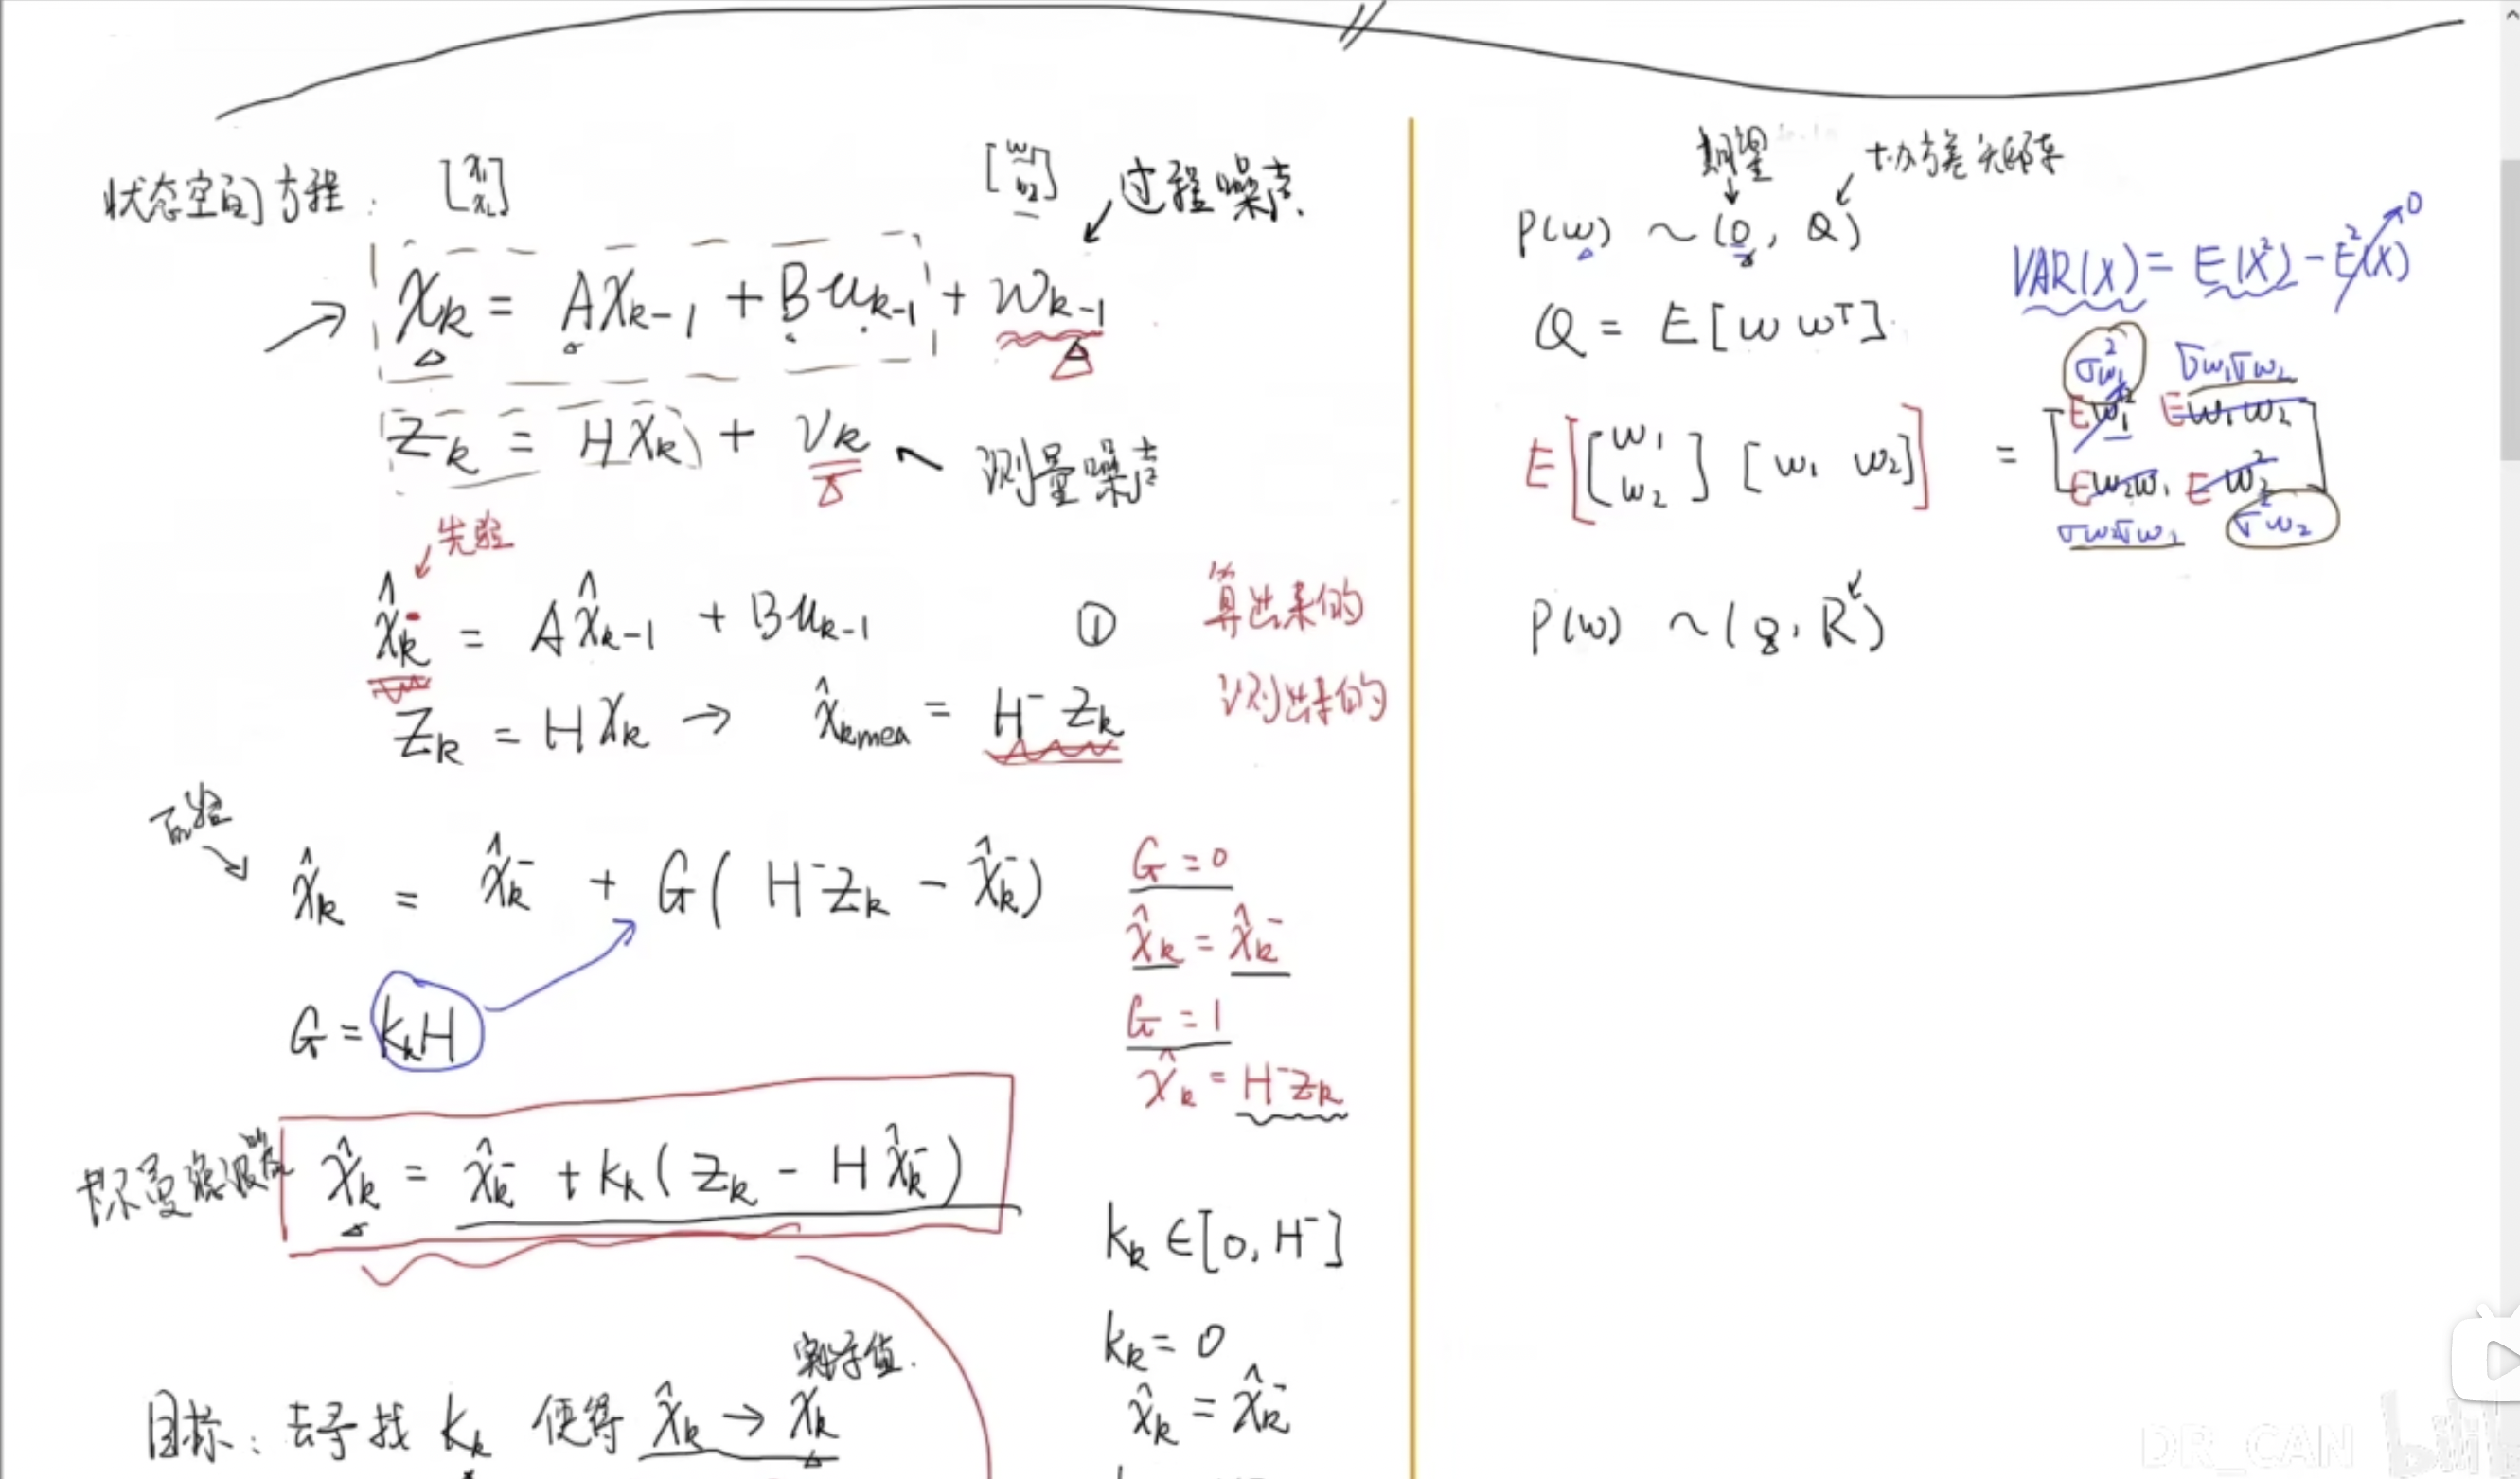
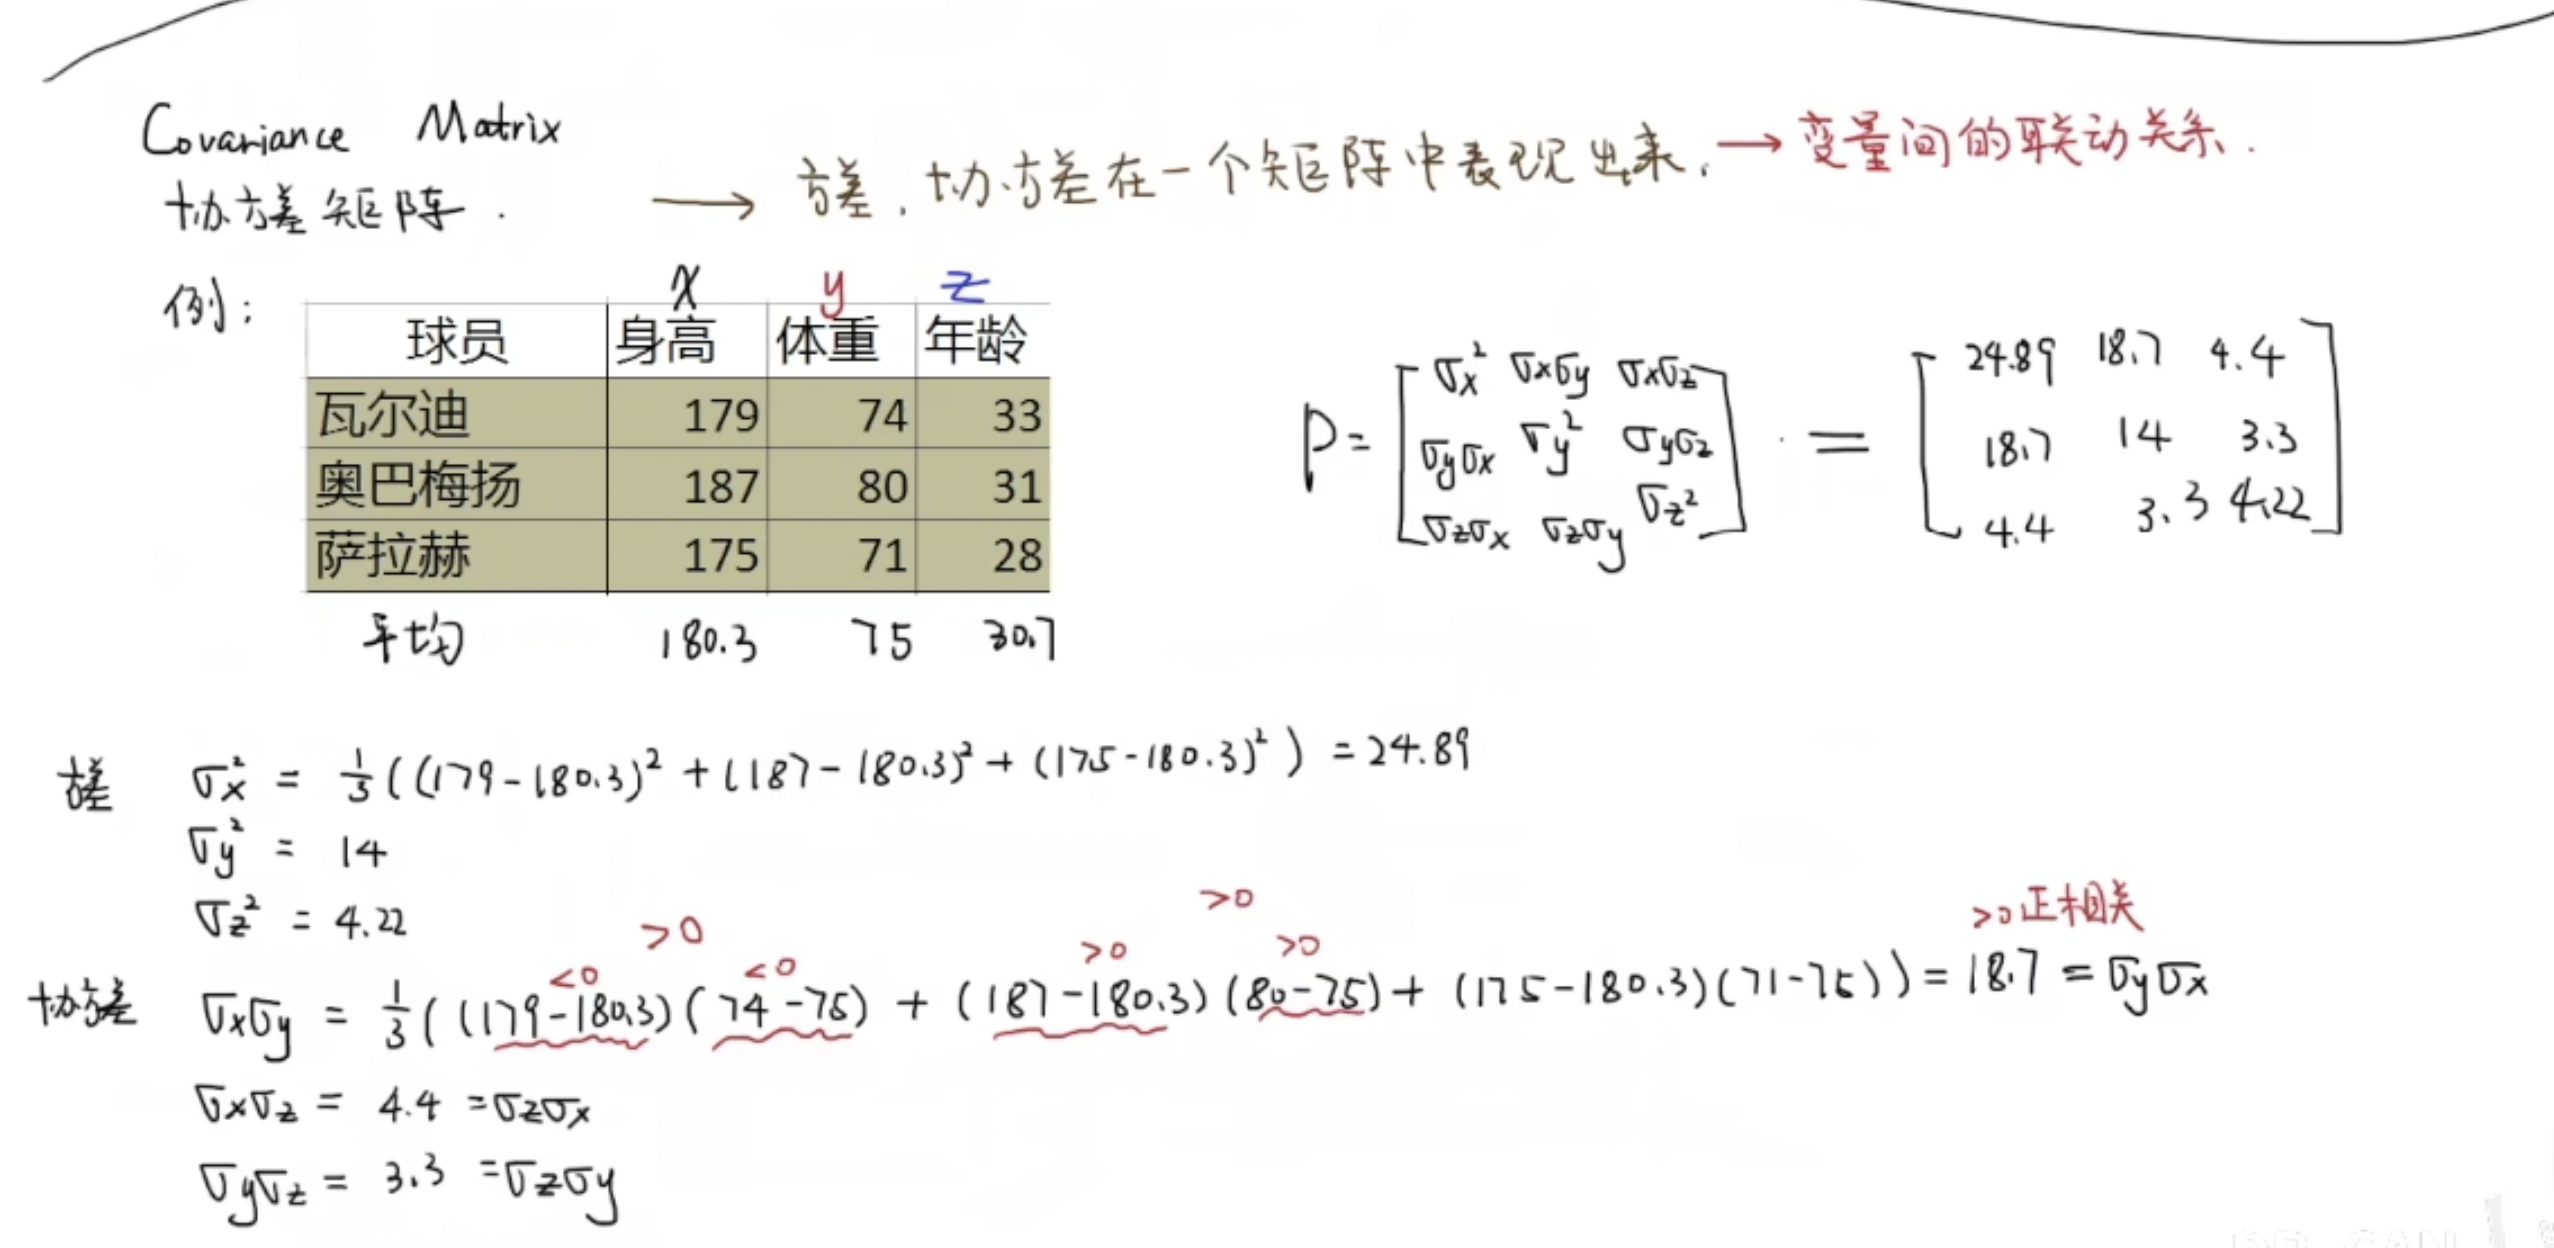
2. Covariance matrix
Variances and covariances are expressed together in one matrix
- A quick way to compute it
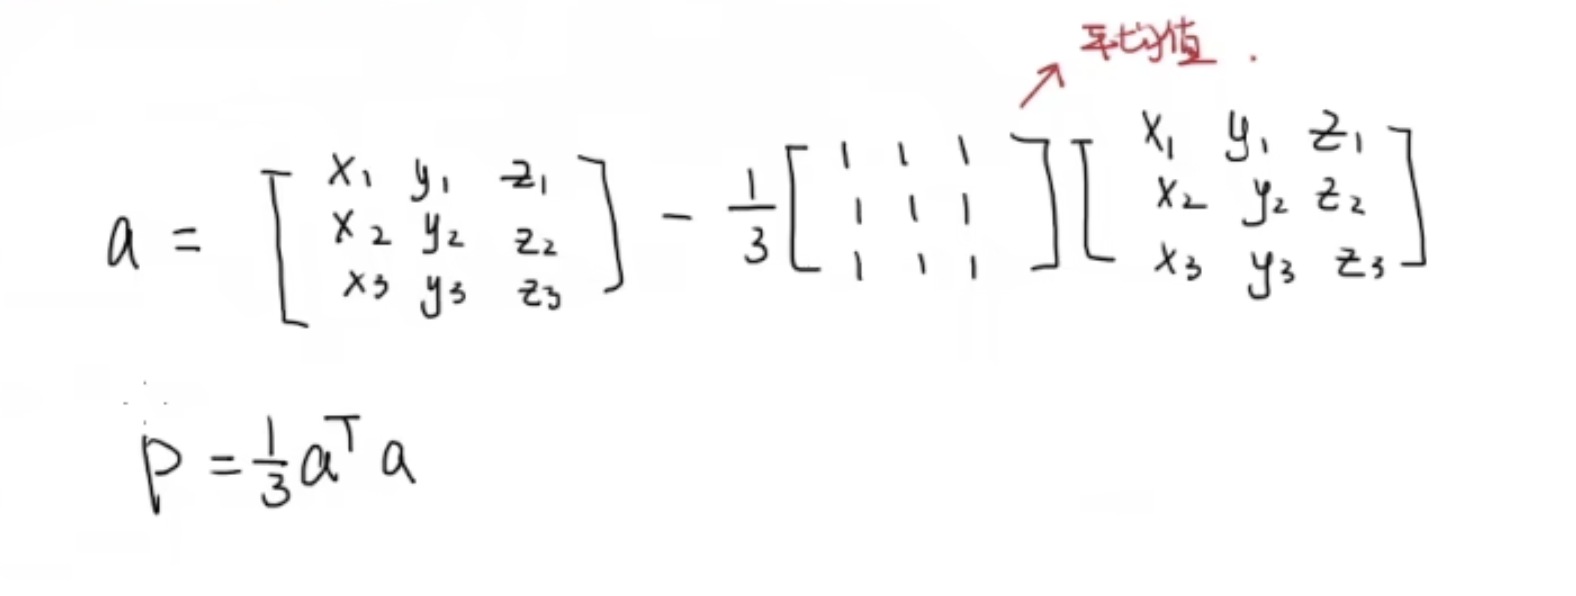
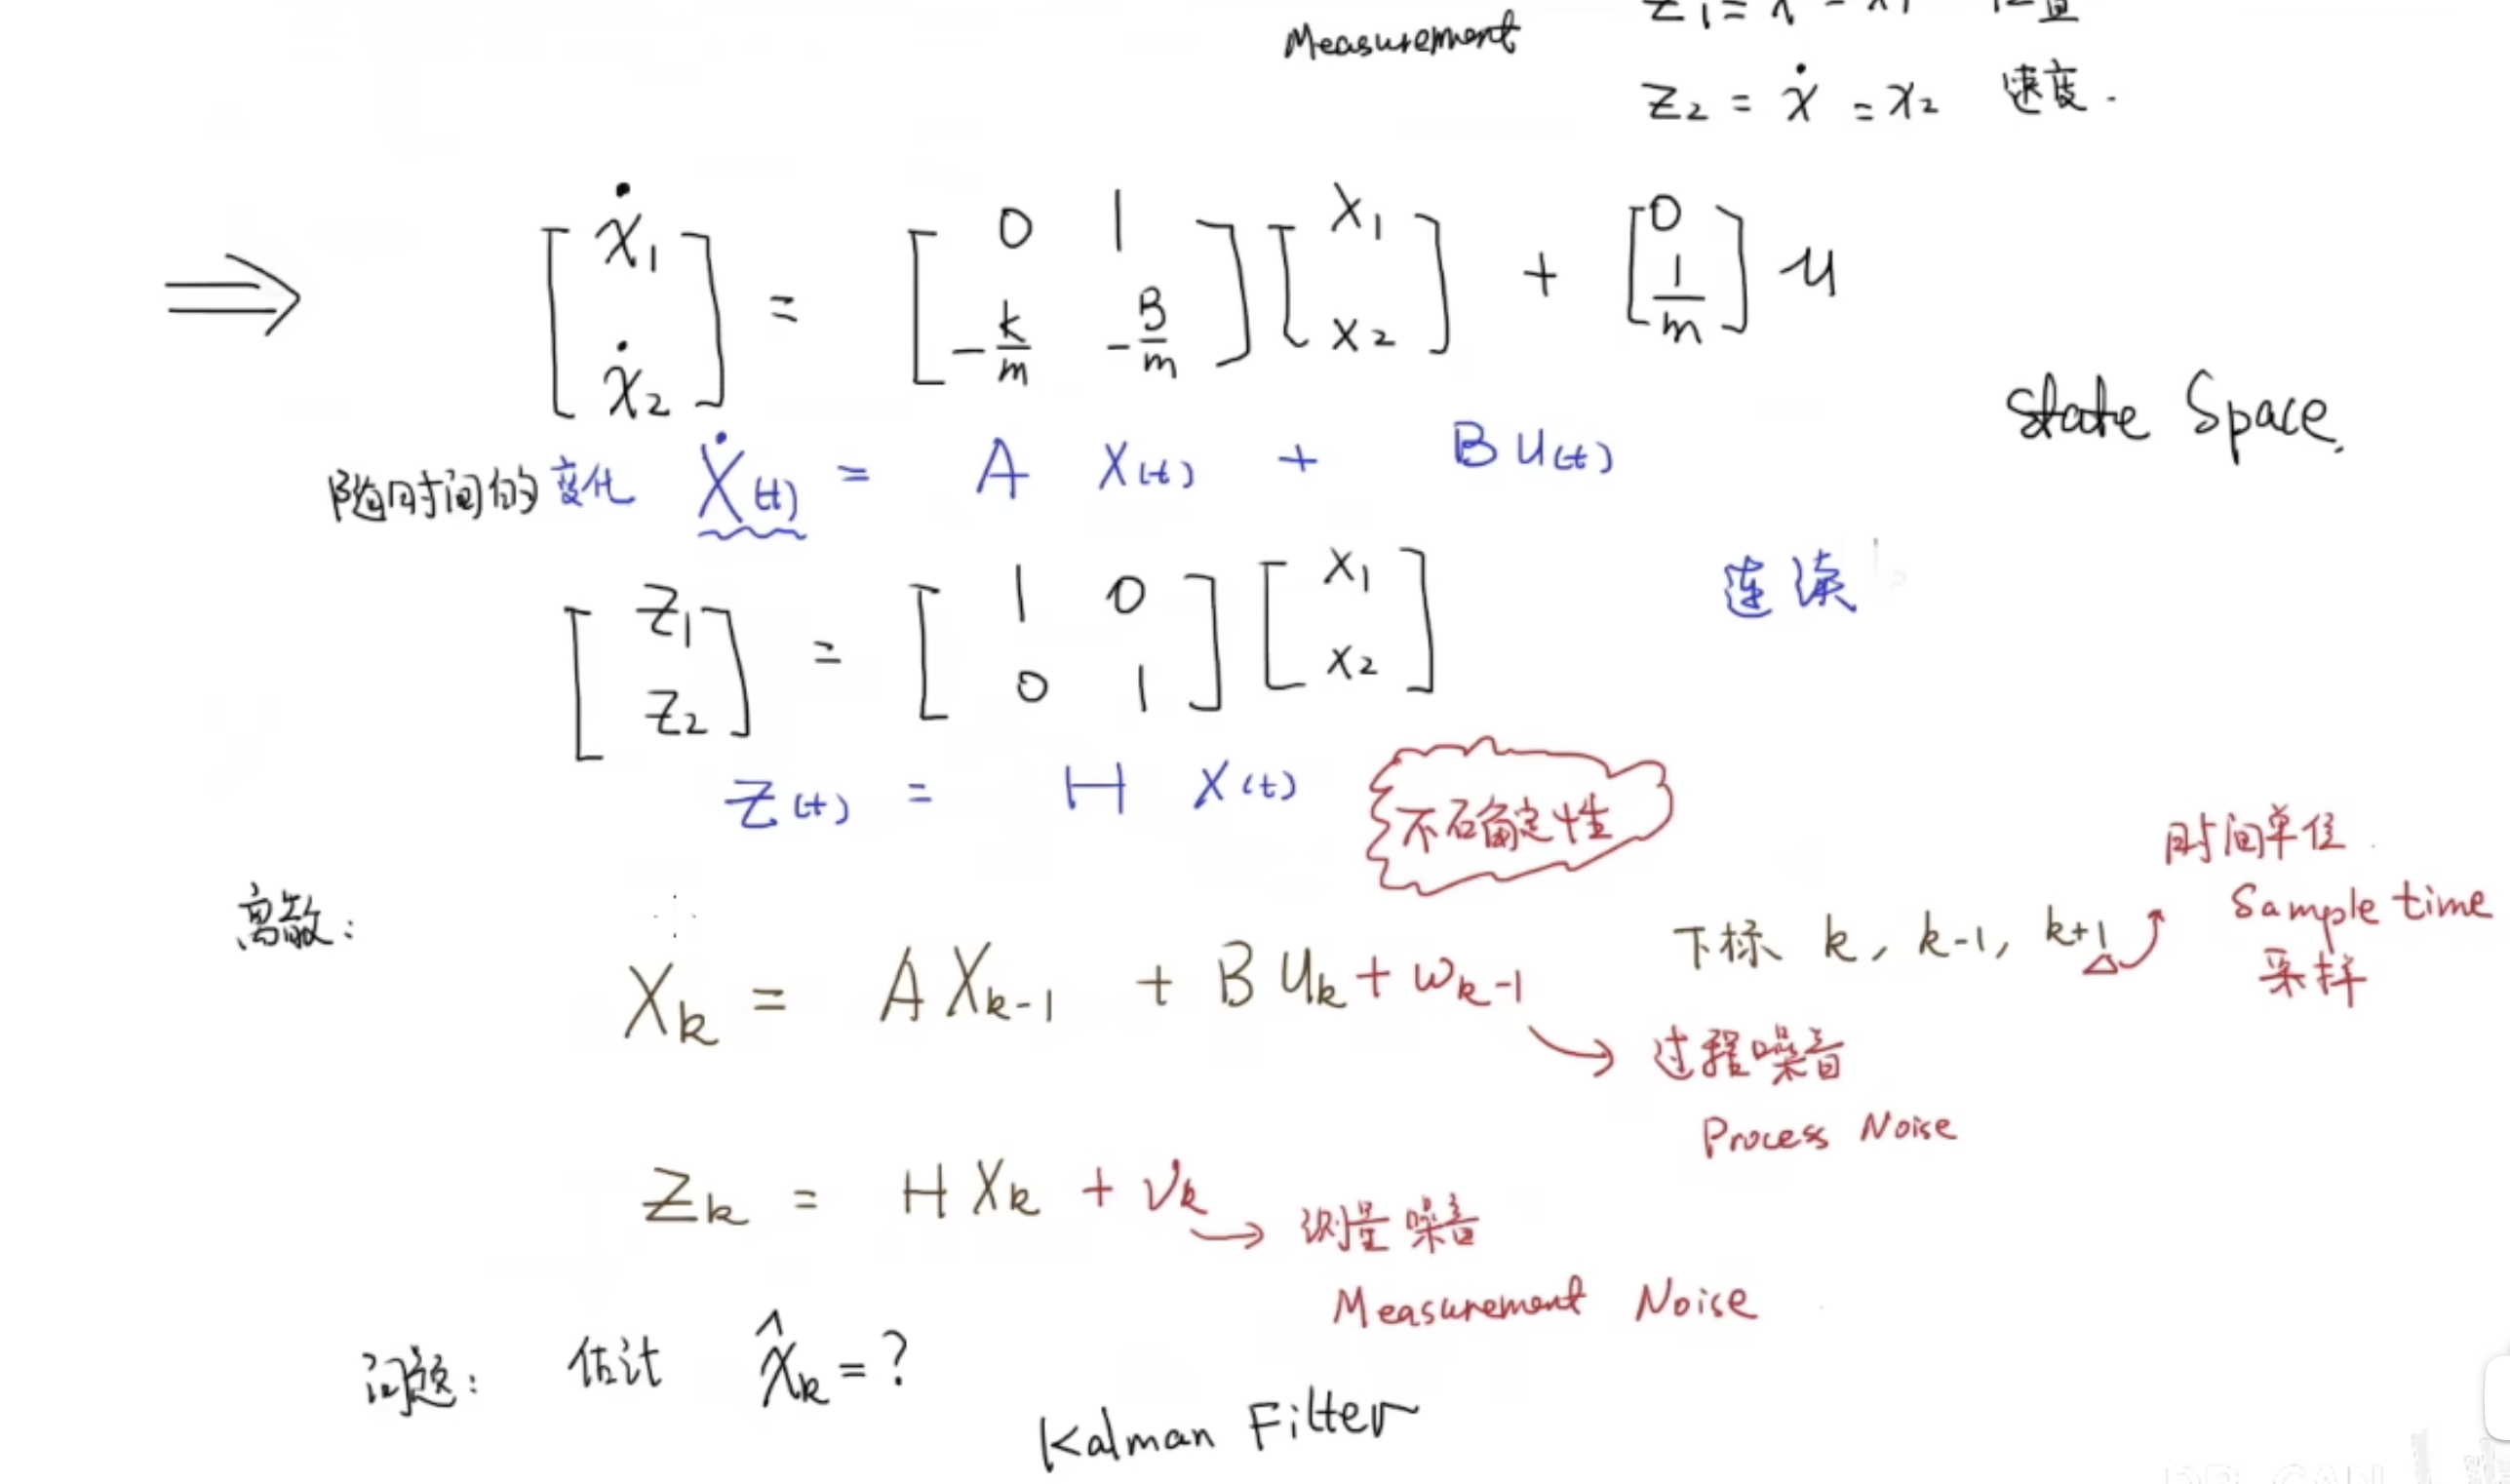
3. State space representation
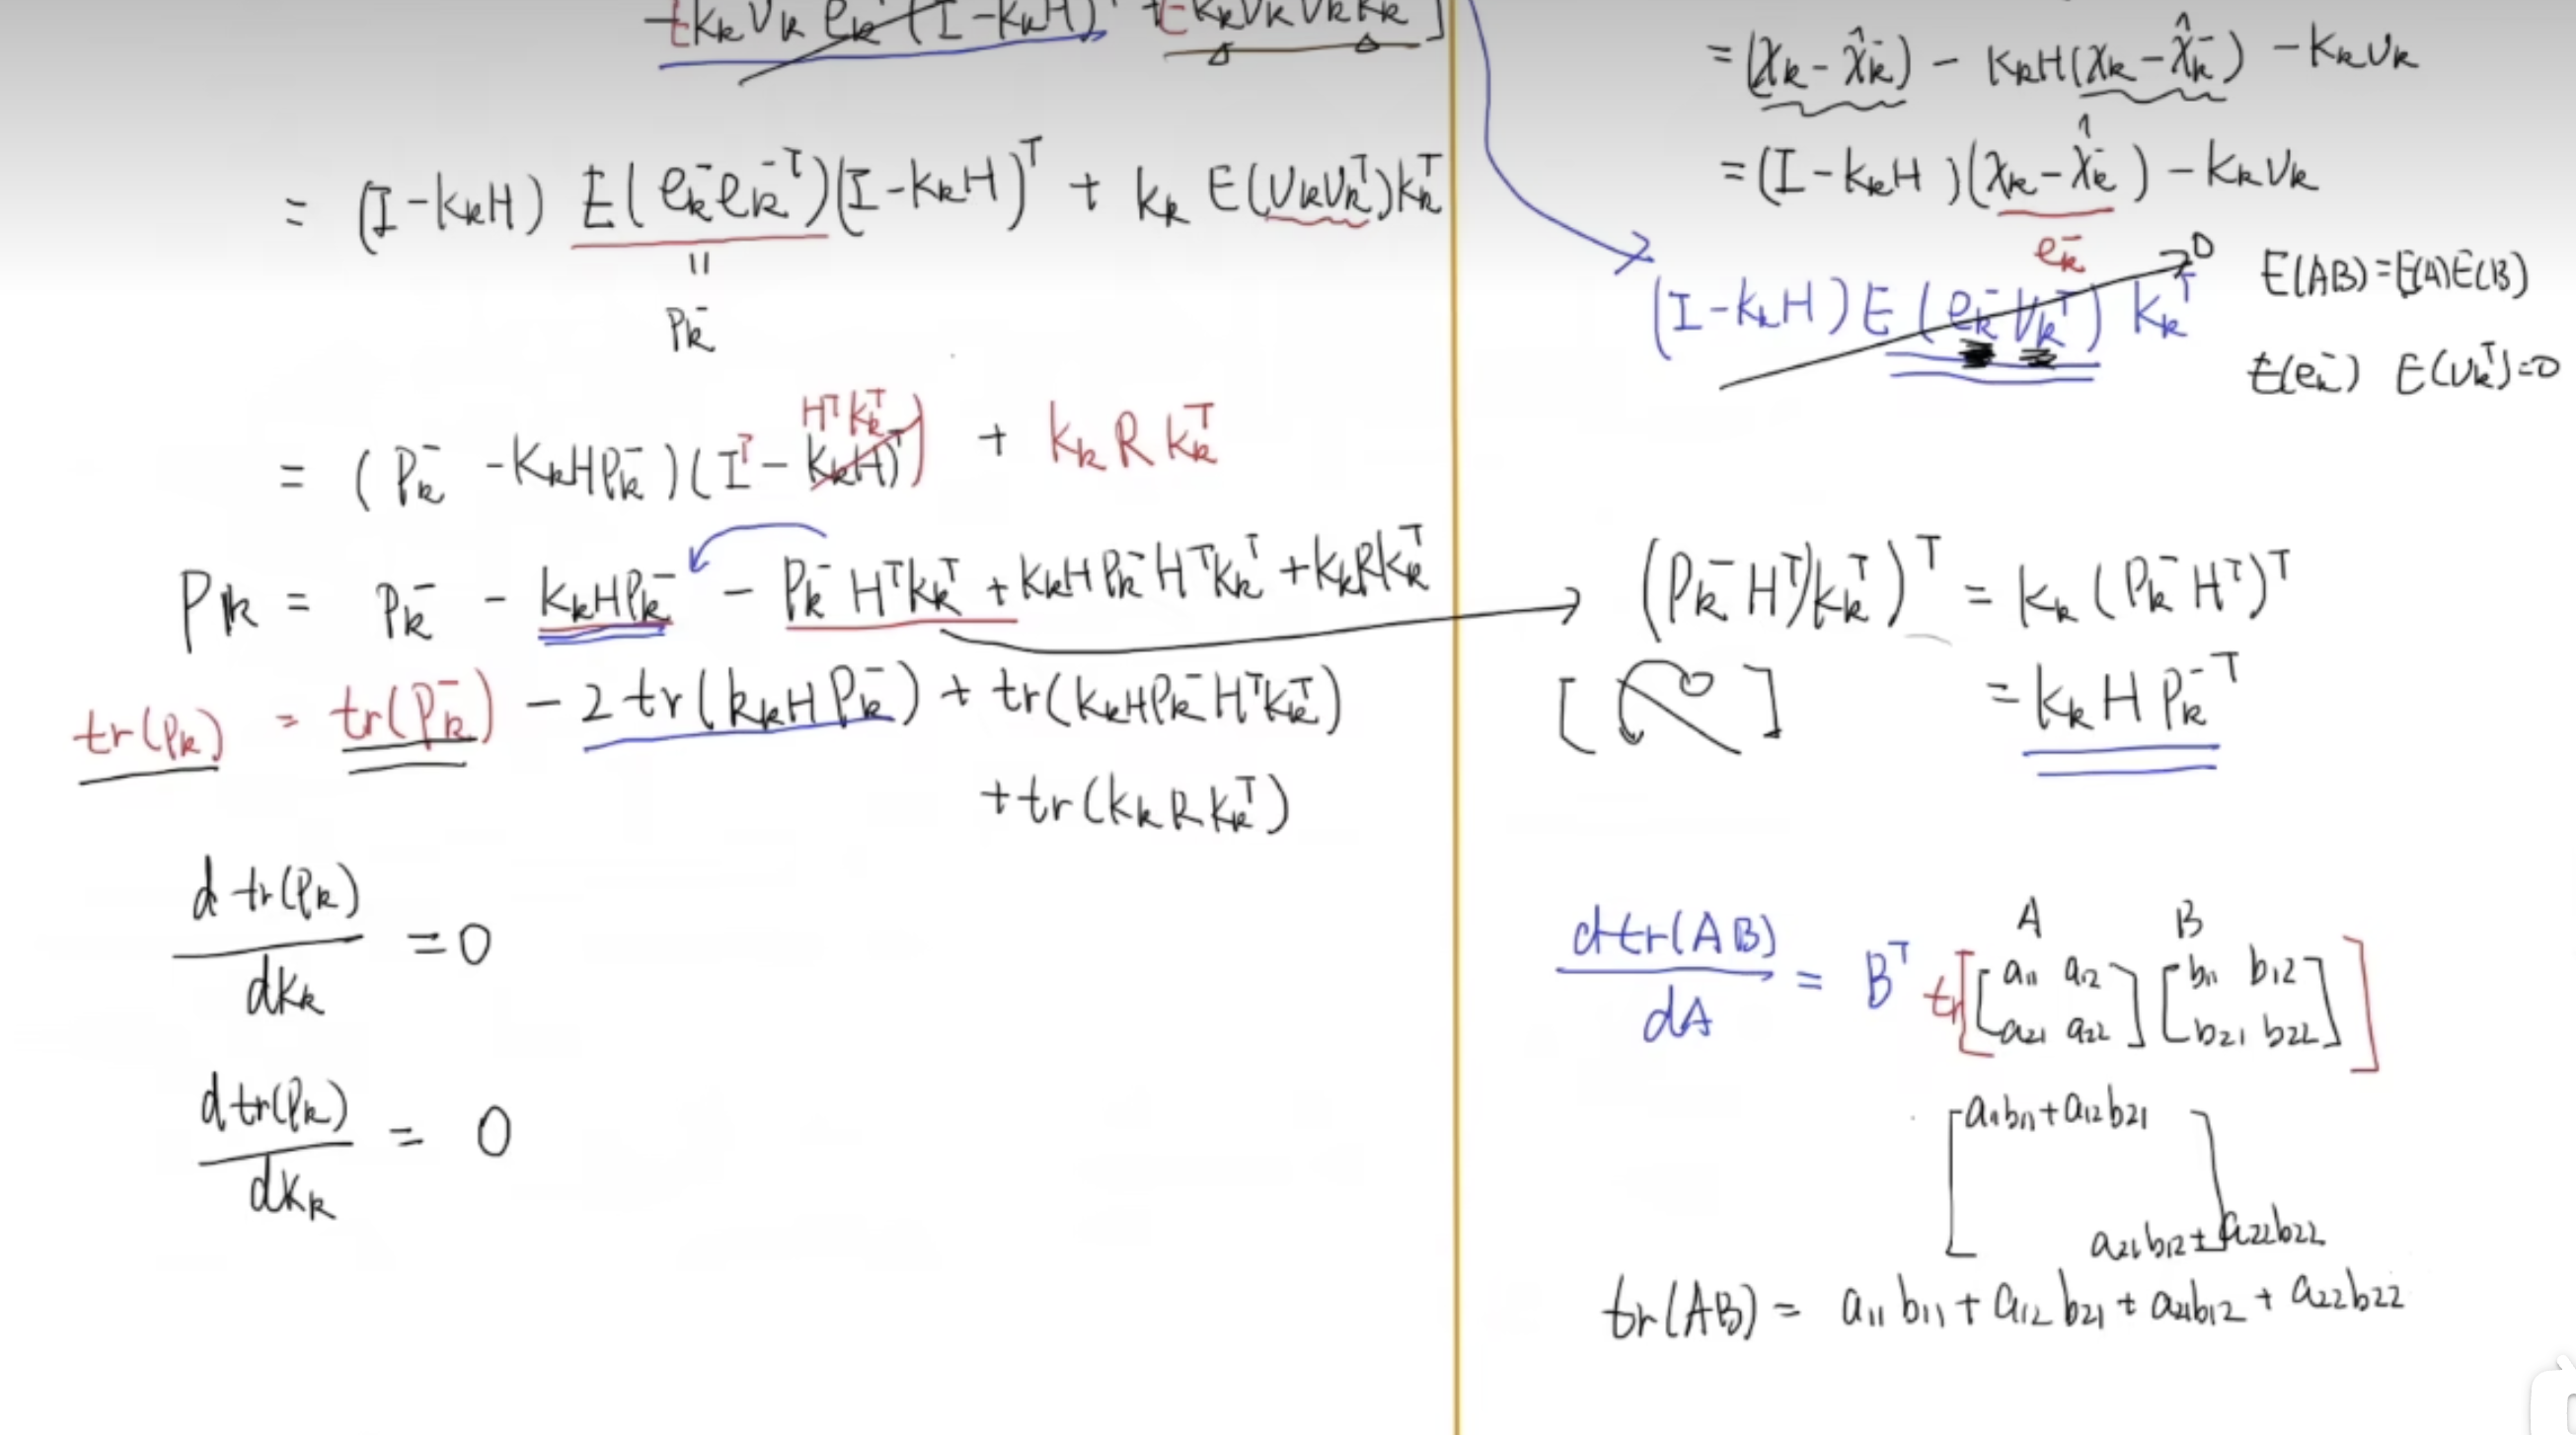
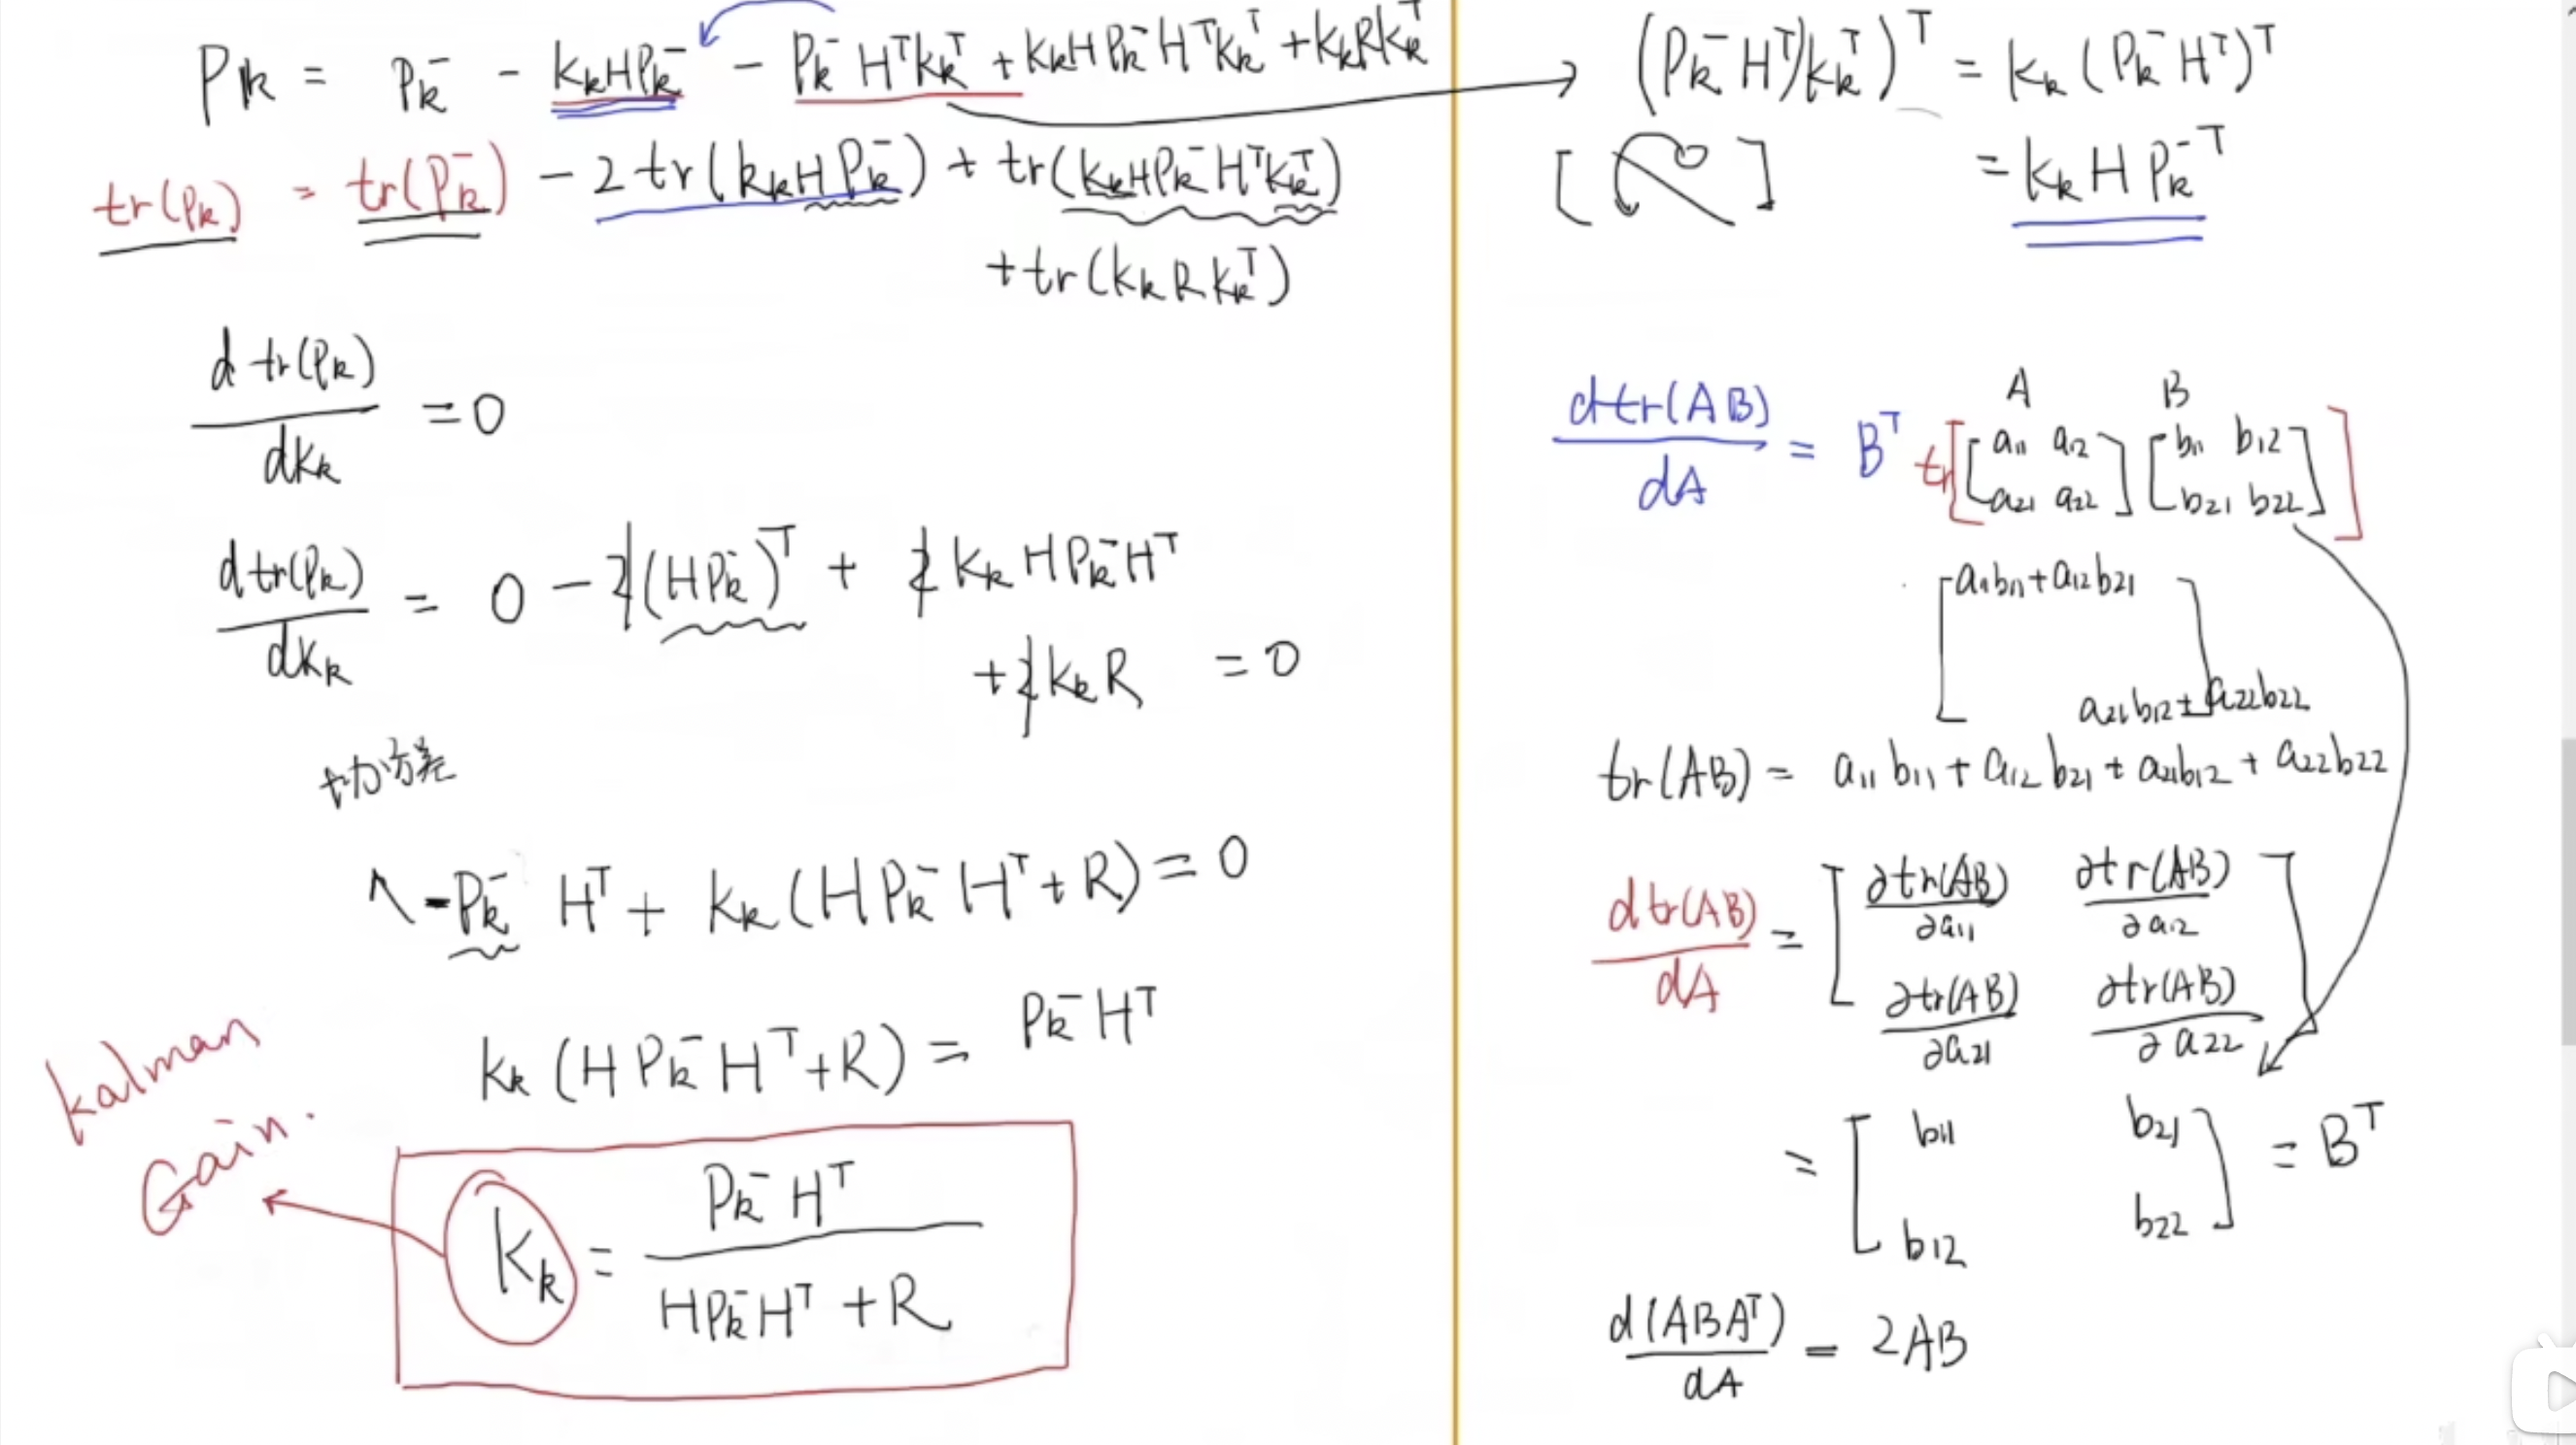
4. Derivation of the formulas